How to Accept Payments in EUR, USD, and Crypto in 2026
How to accept payments in EUR, USD, and crypto in 2026 with Brighty. Discover seamless global payments, low fees, and an all-in-one solution for businesses and freelancers.
How can a business accept crypto and fiat payments?
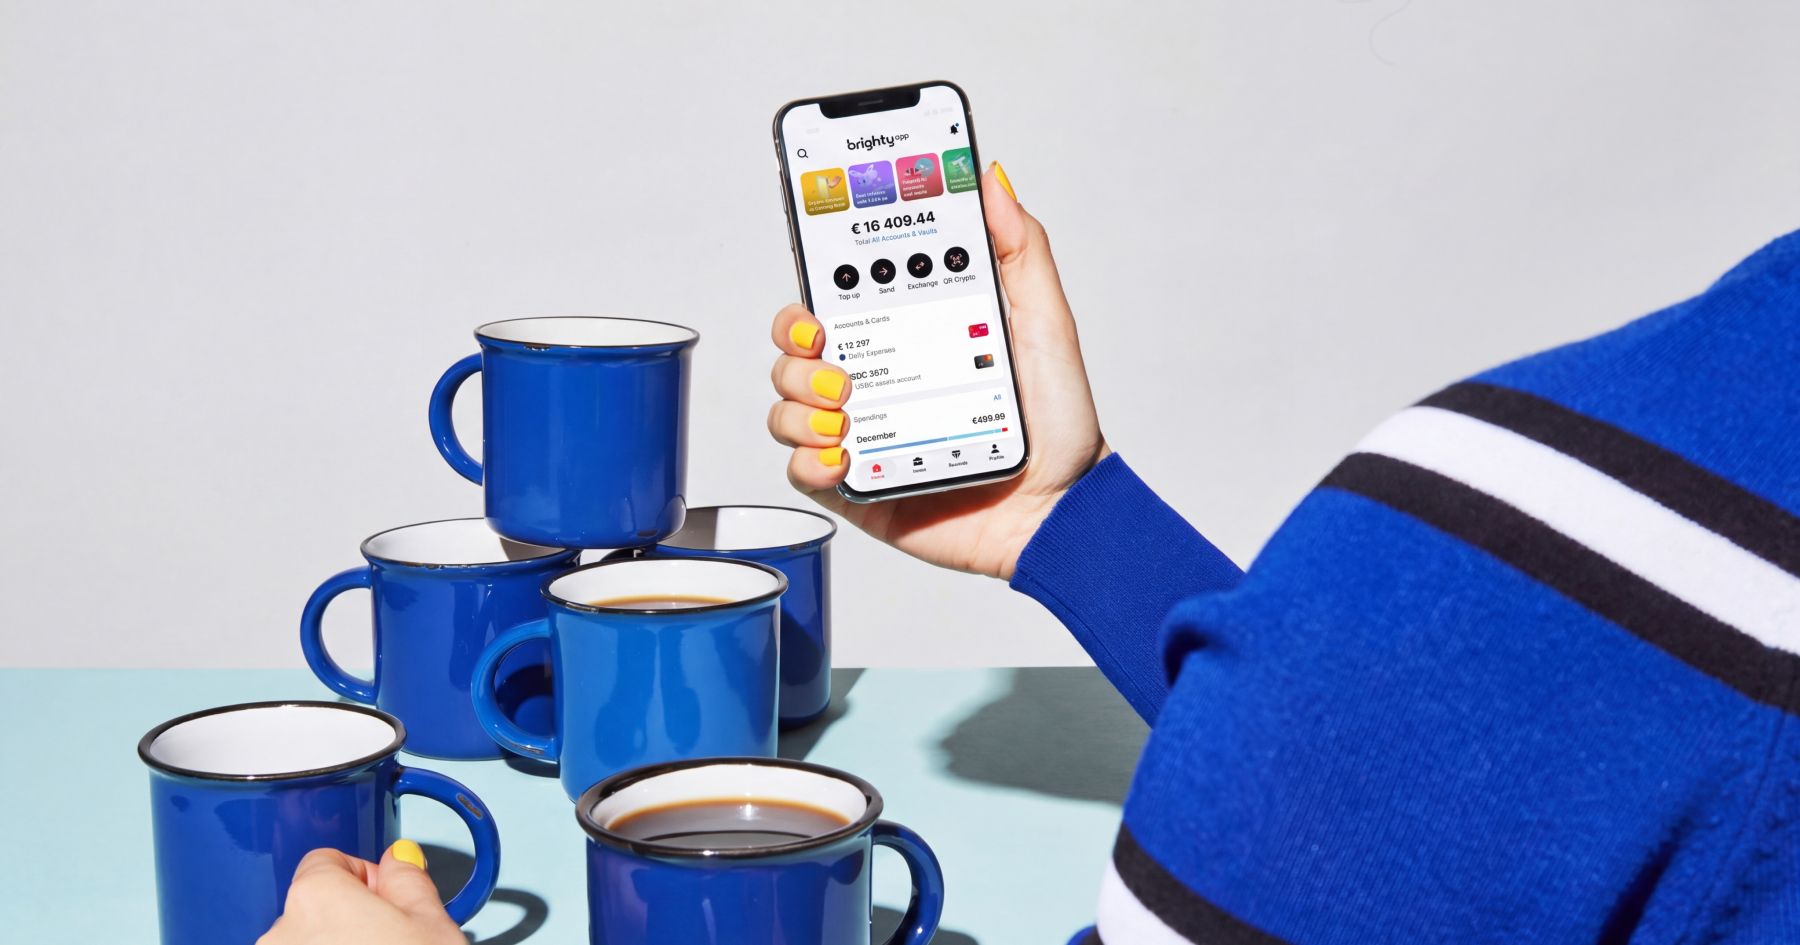
The fastest setup pairs a named IBAN for EUR, USD, and GBP — via SEPA and SWIFT — with a regulated USDC wallet inside one platform that converts between fiat and stablecoins instantly. Brighty handles this end-to-end across the EEA. The comparison table below covers fees and settlement times for every rail in this guide.
Key Takeaways
- EUR payments are easiest via IBAN + SEPA/SEPA Instant
- USD transfers via SWIFT are costly — use multi-currency accounts or stablecoins instead
- Stablecoins such as USDC and EURC enable fast, low-fee cross-border payments
- Best setup: receive in crypto, convert to fiat when needed
- Stablecoin payments are now routine for cross-border work, not an edge case
- All-in-one platforms reduce fees and operational complexity
Anyone invoicing across borders runs into the same wall sooner or later: the money arrives in the wrong currency, or on a rail that costs more than the work was worth. In 2026, the best setups combine a personal IBAN for fiat, stablecoins for cross-border speed, and a single app that handles all of it without the overhead of multiple accounts.
Below: how to get set up, and which tools hold up in practice.
Contents
- Payment methods at a glance
- How to accept EUR payments
- How to accept USD payments
- How to accept crypto and stablecoin payments
- Why multi-currency payment acceptance matters
- Best tools for accepting EUR, USD, and crypto in 2026
- Best practices
- Which payment setup is right for your business?
- FAQ
Payment methods at a glance
A side-by-side view of how each rail performs across fees, speed, and how hard it is to set up.
| Payment method | Tool / platform | Fee | Settlement speed | Integration complexity |
|---|---|---|---|---|
| SEPA (EUR) | Brighty, banks, Wise | 0.3% (min €10) on Brighty; varies elsewhere | Same business day | Low |
| SEPA Instant (EUR) | Brighty, modern EMIs | 0.3% (min €10) on Brighty | Under 10 seconds | Low |
| SWIFT (USD/EUR/GBP) | Brighty, banks, Wise | 0.7% (min €50) on Brighty; $25–$50 flat at legacy banks | 1–5 business days | Low |
| Faster Payments (GBP) | Brighty, UK banks | 0.3% (min €10) on Brighty | Seconds to 2 hours | Low |
| ACH (USD) | Brighty, US banks | Free to receive | 1–3 business days | Low |
| USDC on-chain | Brighty, exchanges, CoinGate | Network fee (cents to a few dollars) | 1–10 minutes | Medium |
| Card processing | Stripe, Adyen | 1.5% + €0.25 per transaction (EU cards) | 1–2 business days | Medium to high |
| Marketplace payouts | Payoneer, Wise | 0%–2% conversion + small withdrawal fee | 1–3 business days | Low (built into the platform) |
How to accept EUR payments
EUR is the simplest piece of the puzzle. Anyone operating in or with the EEA should have a dedicated IBAN — a European bank account number that lets clients pay you via SEPA or SEPA Instant.
SEPA covers 36 countries and processes transfers typically within one business day. SEPA Instant settles in under 10 seconds and is increasingly the default on modern platforms operating under frameworks influenced by the European Central Bank.
What to look for in a EUR payment setup:
- A named IBAN in your own name (not a pooled virtual account)
- SEPA Instant support
- Low or zero receiving fees
- A debit card linked to the balance for everyday spending
Modern neobanks and EMIs (Electronic Money Institutions) provide this without the friction of a traditional bank account. The key difference from a legacy bank is that onboarding takes minutes, not weeks, and the IBAN works from day one.
How to accept USD payments
USD is where things get trickier for non-US users. Without a US bank account or a local routing number, receiving USD from American clients often means going through expensive SWIFT wires that eat into every payment.
There are two practical options in 2026:
1. Multi-currency account with a USD wallet. Some platforms issue dedicated USD IBANs or USD wallets with SWIFT access, letting you receive dollars as if you had a US account. You hold the USD balance and convert when the rate is favourable.
2. Stablecoins such as USDC. For clients comfortable with crypto, receiving payment in USDC is functionally equivalent to receiving USD: same value, near-zero fees, settlement in minutes. You then convert to EUR or hold the stablecoin as needed.
The stablecoin route has become increasingly common for freelancers working with Web3 companies, digital agencies, and international clients who already hold crypto assets.
How to accept crypto and stablecoin payments
Getting paid in crypto used to mean volatility risk and technical friction. In 2026, the stablecoin layer has removed most of that. USDC and USDT are pegged 1:1 to the dollar, so receiving payment in USDC is effectively receiving USD without the banking infrastructure.
Practical setup:
- Get a wallet address (on a regulated platform — not just a self-custody wallet, unless that's intentional)
- Share the address with your client for the relevant network (USDC on Tron is cheapest for small amounts; USDC on Ethereum for larger institutional transfers)
- Convert to EUR/USD when needed, or hold the stablecoin until you do
Key things to consider here:
- Always agree on the amount in fiat (EUR or USD) and convert at time of payment — this avoids disputes over price movements between invoice date and settlement
- Stick to established stablecoins such as USDC and EURC, which publish audited reserve reports
- Check the tax treatment in your country: in many EU jurisdictions, converting stablecoin to fiat is a taxable event, while holding stablecoins may not be
Why multi-currency payment acceptance matters
Traditional banking handles one currency well, but everything else can get messy. A European freelancer receiving USD from a US client via wire transfer can lose 3–5% to FX markups and intermediary fees before the money lands. A business paying international contractors faces reconciliation headaches and compliance obligations that vary by jurisdiction.
By the numbers.
- In a January 2026 PayPal and National Cryptocurrency Association survey, 39% of US merchants already accept cryptocurrency at checkout, and 84% expect crypto payments to become common within five years (PayPal Newsroom, 2026). EU-specific merchant adoption is not yet tracked in a comparable single figure.
- Among those merchants that already accept crypto, it accounts for 26% of total sales, and 72% report year-on-year growth in crypto-related sales (PayPal Newsroom, 2026).
Here’s a practical rundown for multi-currency infrastructure in 2026:
- Stablecoins have gone mainstream. On-chain stablecoin transactions exceeded $1 trillion annually, with USDT and USDC accounting for roughly 90% of stablecoin volume, according to industry data. - Crypto payment infrastructure in the EU has moved out of the grey area it occupied a few years ago, with established providers and published reserve audits. - Bank wire fees are rising, with compliance overhead pushing traditional international transfers to cost 10–15% more in 2026 than just a few years ago.
The right setup eliminates most of these costs and consolidates everything into one workflow.
Best tools for accepting EUR, USD, and crypto in 2026
Brighty — best all-in-one solution for individuals and businesses
Brighty is perhaps the most complete option for anyone who needs EUR, USD, and crypto in a single app. Fiat accounts, cards and custody are provided through licensed partners, so both sides of the account sit on established infrastructure.
What you get with Brighty:
- Personal IBAN for EUR, USD, and GBP: receive SEPA and SWIFT transfers directly
- Crypto wallet supporting BTC, ETH, USDC
- Instant conversion between fiat and crypto at institutional rates
- Free incoming cryptocurrency transfers on every plan
- Virtual cards, Apple Pay and Google Pay compatible
- B2B accounts with mass payouts, API access, and corporate cards for teams
For businesses: Brighty's API handles bulk payments to international contractors in fiat or crypto, automated FX conversion, and multi-chain swaps — all from one dashboard. It's built for agencies, Web3 teams, and anyone managing cross-border payroll.
The key advantage over using separate tools is that there’s one KYC process, one dashboard, etc. There’s no reconciling three different platforms at the end of each month.
Wise — best for low-cost fiat transfers
Wise remains the benchmark for transparent international transfers. It uses the mid-market exchange rate with a clearly stated variable fee, and offers local receiving accounts in EUR, GBP, USD, and others. No crypto support.
- Fees: 0.33–0.75% conversion fee depending on currency pair - Speed: 74% of transfers complete in under 20 seconds - Best for: freelancers receiving direct bank transfers from EU, UK, or US clients
Payoneer — best for marketplace freelancers
Payoneer integrates directly with Upwork, Fiverr, Amazon, and 2,000+ other platforms. It also has a reach across 190+ countries, including markets where traditional banking is limited.
- Fees: free to receive from integrated marketplaces; 0.5–2% on currency conversion; $1.50 per bank withdrawal - Watch out: $29.95 annual inactivity fee if you receive under $2,000/year - Best for: freelancers whose primary income comes through global platforms
CoinGate — best for crypto-native payment processing
CoinGate is specifically built for businesses that need to send and receive crypto. It supports USDC, BTC, ETH, and others across multiple chains.
- Fees: €0.50 + 0.5% for standard crypto payouts; €0.50 + 1.5% with FX conversion - Best for: agencies and platforms that need automated stablecoin payouts to contractors or partners at scale
Brighty vs Wise vs Payoneer vs CoinGate: side-by-side
| Platform | EUR IBAN | USD wallet | Crypto | Cards | Best for |
|---|---|---|---|---|---|
| Brighty | Yes | Yes | Yes (BTC, ETH, USDC, EURC) | Virtual + physical | All-in-one: individuals and businesses |
| Wise | Yes | Yes | No | Debit card | Low-cost fiat FX |
| Payoneer | Yes | Yes | No | Mastercard | Marketplace freelancers |
| CoinGate | No | No | Yes | No | Crypto payouts at scale |
Best practices
Use stablecoins for cross-border speed, fiat rails for settlement. The most efficient workflow option: receive USDC from international clients, convert to EUR via an integrated platform when needed, and spend from your debit card. This eliminates 3–5% wire fees.
Keep one account for everything where possible. Splitting between a fiat account, a crypto wallet, and a card means three reconciliations and three sets of compliance documentation. Platforms like Brighty collapse that into one.
Invoice in fiat, settle in whatever the client prefers. State your rate in EUR or USD. If the client pays in USDC, convert at time of receipt. This protects you from volatility disputes and simplifies accounting.
Check your country's crypto tax rules. Converting stablecoin to fiat is a taxable event in most EU jurisdictions. Use a platform with clean transaction history exports for your accountant.
Which payment setup is right for your business?
In 2026, there's no good reason to run a separate bank account, crypto wallet, and payment processor when a single regulated platform handles all three. The friction of multi-currency payment acceptance has largely been solved — the remaining work is picking the right stack for your situation.
For most individuals and small businesses across the EEA, the answer is a platform with a named IBAN, stablecoin support, and integrated conversion. Brighty covers all of that in one app.
FAQ
Can a business accept both crypto and fiat payments from one account?
Yes. Platforms like Brighty hold a named IBAN for EUR, USD, and GBP alongside a USDC wallet under the same account, with instant conversion between them. This removes the need to run a separate bank account, exchange, and payment processor.
Is it legal for EU businesses to accept stablecoin payments in 2026?
Yes. Stablecoins from established issuers, including USDC and EURC, are widely accepted for business payments across the EU. Check who issues the stablecoin you accept and whether it publishes reserve audits.
What's the cheapest way to receive USD payments in Europe?
For clients comfortable with crypto, receiving USDC settles in minutes with network fees under a dollar. For traditional payments, a multi-currency account with a dedicated USD wallet beats SWIFT, which can cost $25–$50 per transfer plus FX markups at legacy banks.
How long do international fiat payments take to settle?
SEPA Instant settles in under 10 seconds inside the eurozone. Standard SEPA takes one business day. SWIFT typically takes one to five business days depending on the corresponding bank chain. ACH (USD) is one to three business days. Stablecoin transfers settle in 1–10 minutes on most networks.
Do I need a registered business to accept crypto payments?
No, freelancers and sole traders can accept crypto on personal accounts at regulated platforms. For higher volumes or B2B work, a registered business account unlocks API access, mass payouts, and clearer accounting separation. Tax obligations apply either way, so check local rules.
What's the difference between USDC and USDT for accepting payments?
Both are dollar-pegged stablecoins, but USDC is issued by Circle under US and EU regulation with monthly audited reserves, while USDT is issued by Tether with less stringent disclosure. EU platforms generally favour USDC and EURC. Brighty supports USDC.
Skip the multi-account setup. Download Brighty for a named EUR/USD/GBP IBAN and a USDC wallet in one place.