How to Hold Crypto and Fiat in One Account: A Look at Hybrid Financial Services
Most people run a bank account and an exchange separately, paying for the gap. Here are the three ways to combine them, plus an 8-point checklist.
How do you hold crypto and fiat in the same account?
Through a hybrid service that pairs a named IBAN with a custodial crypto wallet under one login, so euros and digital assets sit side by side and convert between each other in-app. Three architectures do this differently, and the 8-point checklist below separates the ones worth using.
Key Takeaways
- A hybrid account combines a named IBAN for fiat with custodial crypto storage, removing the transfers people otherwise make between a bank and an exchange.
- Incoming SEPA payments are free to receive under EU rules that cap cross-border euro transfers at the domestic price (European Central Bank, Single Euro Payments Area, 2025).
- On Brighty, conversion between held currencies runs 0.6% on One, 0.5% on Plus and 0.4% on Pro, above free monthly allowances of €0, €2,000 and €5,000 (Brighty, Fees and Limits, 2026).
- Card spending carries no monthly service fee on any Brighty plan, though a Visa purchase in a currency you don’t hold adds 2% (Brighty, Fees and Limits, 2026).
- The crypto side sits outside the €100,000 deposit guarantee that covers EU bank deposits, so concentration risk deserves attention (European Banking Authority, Deposit Guarantee Schemes Data).
- Hybrid accounts are custodial by design, since holding both asset types under one login requires the provider to control the crypto keys.
In This Article
- What is a hybrid financial service?
- What are the three ways to hold crypto and fiat together?
- What should you check before choosing a hybrid account?
- What does running a hybrid account cost?
- What are the trade-offs of combining both in one place?
- How Brighty works as a hybrid account
- FAQ
What is a hybrid financial service?
A hybrid financial service holds traditional currency and digital assets in the same account, with conversion between them built in. The practical test is whether a salary can arrive as euros and leave as a stablecoin without touching a second platform.
The category exists because of a gap in how most people operate. A bank account handles everyday money while an exchange handles crypto, and moving value between them means a transfer that takes time and usually costs something at each end. A hybrid account collapses that round trip into an in-app conversion.
Behind the interface, two systems report into one balance screen. The fiat side works through a named IBAN receiving payments over standard rails, where incoming SEPA transfers cost nothing under EU pricing rules (ECB, Single Euro Payments Area, 2025) and SEPA Instant credits within ten seconds (ECB, Instant Payments Regulation, 2024). The crypto side is custodial, which is what allows an instant internal conversion. Swapping euros for a stablecoin inside the account is a book entry rather than a blockchain transaction, so it settles immediately and pays no network fee.
What are the three ways to hold crypto and fiat together?
Three architectures solve this problem with very different amounts of friction. The differences show up in how many logins are involved and how long a conversion takes.
| Approach | How it works | Friction | Best suited to |
|---|---|---|---|
| Bank plus exchange | Separate accounts, manual transfers between them | High. Two logins, transfer delays, fees at each end | People whose crypto and fiat activity rarely interact |
| Exchange with fiat rails | An exchange offering deposits and sometimes a card | Medium. One login, though built for trading rather than daily banking | Active traders who occasionally spend |
| Hybrid account | IBAN and crypto wallet under one login, conversion in-app | Low. One login, instant conversion, card attached | People whose income or spending crosses both regularly |
The right choice depends on how often the two sides touch. Someone who buys crypto twice a year gains little from a hybrid account. Someone receiving payments in stablecoins and paying rent in euros is doing that round trip constantly, and that is where the friction adds up.
What should you check before choosing a hybrid account?
Eight questions separate a genuine hybrid account from a crypto app with a payment feature bolted on. Working through them prevents the common mistake of opening an account that cannot do the one thing you needed.
- Is the IBAN in your own name? Named IBANs accept salary payments and direct debits. Pooled or reference-based accounts often get rejected by payroll systems.
- Which fiat currencies are supported? Holding EUR alone is limiting if clients pay in USD or GBP, since every incoming payment then needs converting.
- What does conversion cost, and is there a free allowance? The allowance often matters more than the headline percentage for modest monthly volumes.
- Which crypto assets are supported? Support for the specific stablecoin you use matters more than a long asset list.
- Is a card included, and on which network? Network affects foreign transaction fees, and some providers price their own card products very differently.
- What are the incoming and outgoing payment fees? Free incoming SEPA is common. Outgoing transfers and international rails usually carry a charge worth checking first.
- Can idle balances earn anything? Where they can, check whether funds are locked and what the live rate is rather than the advertised ceiling.
- How does the provider hold customer assets? The crypto side is custodial, so provider disclosures replace the deposit protection that does not apply here.
A shortcut for anyone in a hurry: questions 1 and 4 disqualify most unsuitable options immediately. An account without a named IBAN cannot receive a salary, and an account without your stablecoin cannot remove the second platform.
What does running a hybrid account cost?
Costs attach to conversion and to moving money out, rather than to a headline account fee. Receiving is generally cheap while converting or sending onward carries small percentages.
Using Brighty’s published figures (Brighty, Fees and Limits, 2026):
| Action | Cost |
|---|---|
| Receiving a SEPA payment in euros | Free |
| Receiving internationally via SWIFT | 0.7%, minimum €12 |
| Converting between held currencies | 0.6% One, 0.5% Plus, 0.4% Pro, above allowances of €0, €2,000, €5,000 |
| Holding a card | Free monthly service fee, all plans and card types |
| Card purchase in a currency you hold | No conversion cost |
| Card purchase in a currency you don’t hold | 2% on Visa. None listed on virtual Mastercard |
| Sending internationally via SWIFT | 0.9%, minimum €30 |
The line that surprises people is SWIFT. International transfers outside the SEPA zone carry real percentage costs at both ends, which makes a hybrid account cheapest for euro payments inside Europe and for stablecoin transfers, with SWIFT being the most expensive option of the three.
Comparing against the alternative is the useful exercise. Running a bank account plus a separate exchange means paying transfer costs and waiting on settlement each time value crosses between them. One in-app conversion at 0.4% to 0.6% often costs less than that whole round trip once time is counted.
What are the trade-offs of combining both in one place?
Convenience concentrates risk. Putting an entire financial life behind one login means a single provider failure or account freeze reaches everything at once, including the salary that has not been spent yet.
Protection is uneven across the two sides. Crypto held in a hybrid account falls outside the €100,000 deposit guarantee covering EU bank deposits, because that framework applies to deposits at banks (European Banking Authority, Deposit Guarantee Schemes Data). Reading a provider’s custody disclosures replaces the assumption of statutory cover. Custody is the second trade-off, since instant in-app conversion requires the provider to control the keys. That buys password recovery at the cost of counterparty exposure.
The practical response mirrors the advice for any concentration. Keep in the hybrid account what it is for, meaning a working balance sized around incoming payments and near-term spending. Long-term crypto holdings of significant size belong in self-custody, and money that must be intact on a specific date belongs somewhere with deposit protection.
How Brighty works as a hybrid account
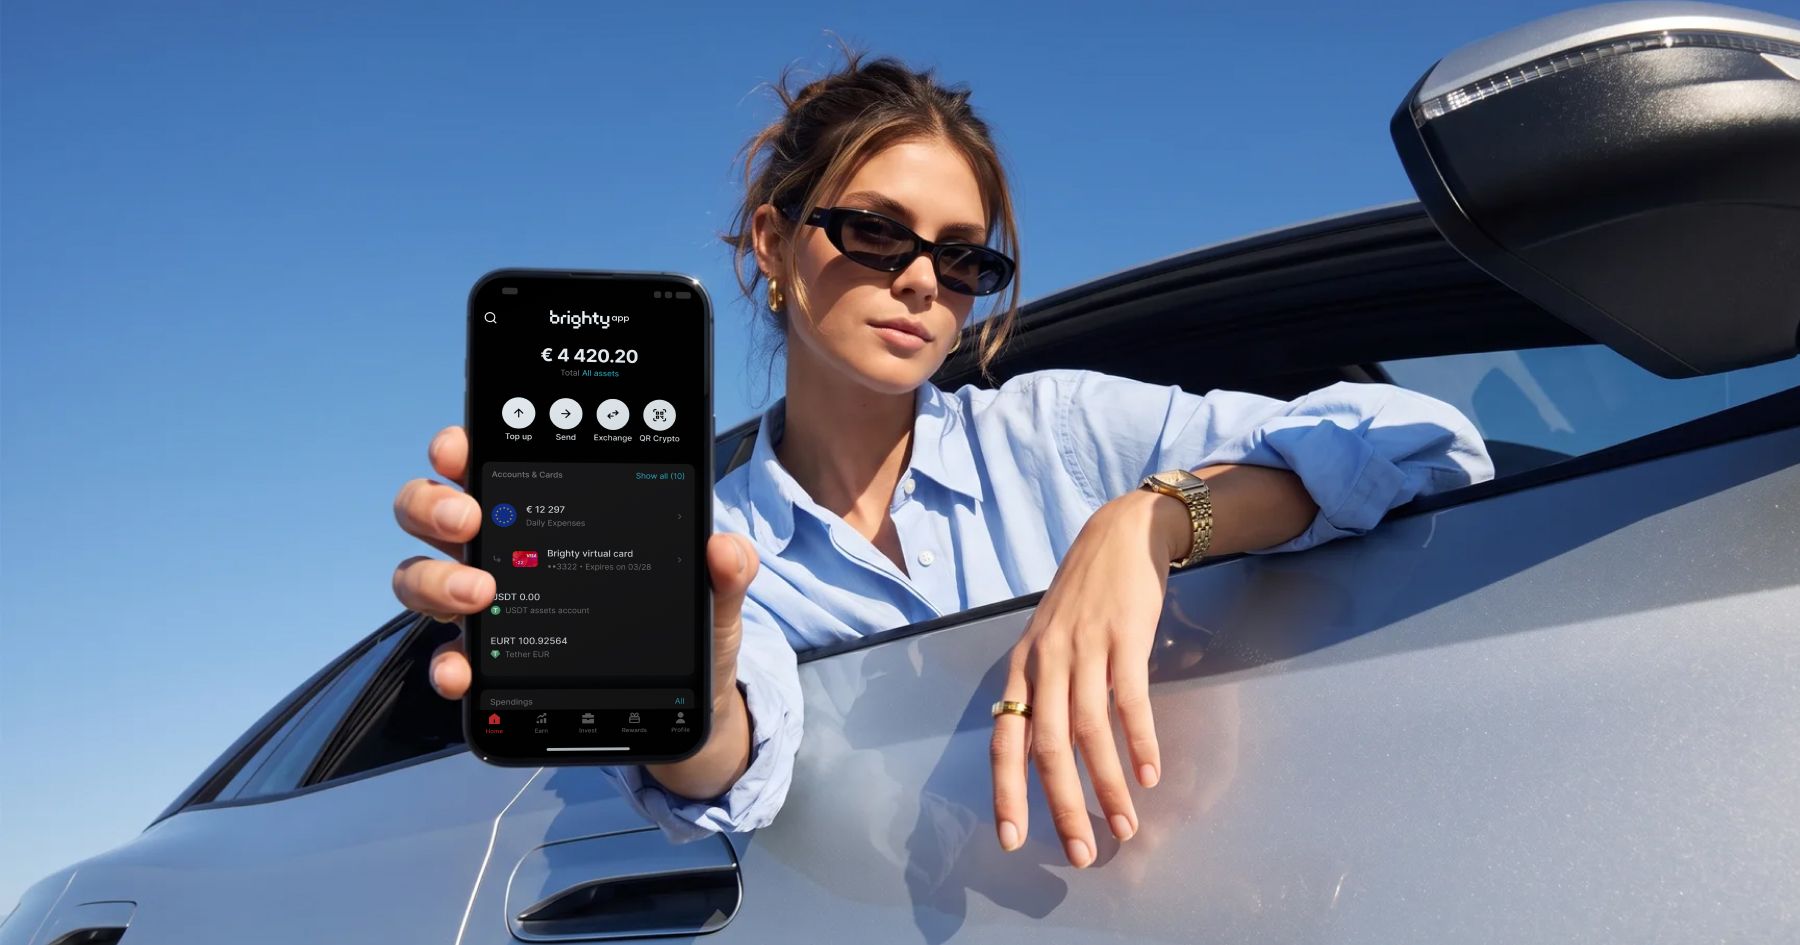
Brighty runs both sides in one app, with a named IBAN in EUR, USD or GBP alongside custodial crypto storage. A client payment can arrive as euros over SEPA, convert to a stablecoin in-app, and be spent from a card without leaving the account.
Incoming rails cover the situations most people encounter:
- SEPA and SEPA Instant for euros, free to receive
- SWIFT for other currencies, at 0.7% incoming with a €12 minimum
- Faster Payments for GBP from UK senders
- ACH and Fedwire for USD from US senders
- USDC on-chain from crypto-capable senders
Conversion runs 0.4% to 0.6% by plan tier above the free allowance, and cards carry no monthly service fee (Brighty, Fees and Limits, 2026). Stablecoin balances can earn yield in Earning Vaults through Aave with no locked funds (Brighty, Homepage, 2026), which addresses the usual problem of a balance sitting idle between payments.
Two caveats belong here. The One plan has a €0 free conversion allowance, so it converts at the full 0.6% from the first euro, making the paid tiers better value for regular converters. And the crypto side is custodial, so the sizing advice above applies here as much as anywhere.
FAQ
Can a hybrid account replace my bank account?
For most day-to-day purposes, yes. A named IBAN receives salary and sends transfers while an attached card handles spending. What it lacks is deposit guarantee protection on the crypto side and access to credit, which is why many people keep a bank account alongside.
Is my crypto safe in a hybrid account?
It is held custodially, so the provider controls the keys and can restore access if you lose your password. Counterparty risk applies in exchange, and no deposit guarantee scheme covers crypto (European Banking Authority).
How fast is converting between fiat and crypto in one account?
Effectively instant. The conversion happens inside the provider’s own books rather than on a blockchain, removing both confirmation time and network fees.
Do I pay tax when converting inside a hybrid account?
Converting crypto to fiat is generally treated as a disposal in European jurisdictions, whether it happens on an exchange or inside a hybrid account. The venue does not change the treatment.
Can I receive my salary into a hybrid account?
If the IBAN is in your own name, usually yes. Payroll systems commonly reject pooled or reference-based account details, which is why the name on the IBAN is worth checking before switching.
Which is better for holding long-term crypto?
Self-custody, for holdings of significant size. A hybrid account suits a working balance for income and spending, while long-term holdings avoid counterparty risk entirely in a wallet where you hold the keys.
Download Brighty to hold euros and stablecoins in one account with a named IBAN and a card attached, and convert between them whenever you need to.